Monday, August 5, 2013

Misconceptions About Valuation

 In a 2012 Valuation Roundtable of San Francisco’s 26th Annual Seminar, keynote speaker Aswath Damodaran (Professor of Finance at the NYU Stern School of Business) presented the myths of valuation.

Myth One: A valuation is an objective search for “true” value

  • Truth: All valuations are biased. The only questions are how much and in which direction.
  • Truth: The direction and magnitude of the bias in a valuation is directly proportional to who pays the valuator and how much that valuator is paid.


Myth Two: A good valuation provides a precise estimate of value

  • Truth: There are no precise valuations.
  • Truth: The payoff to valuation is greatest when valuation is least precise.


Myth Three: The more quantitative a model, the better the valuation

  • Truth: One’s understanding of a valuation model is inversely proportional to the number of inputs required for the model.
  • Truth: Simpler valuation models do much better than complex ones.

Sources:

  1. Blog; Aswath Damodaran Explains 3 Misconceptions About Valuation
  2. Original presentation
  3. PPT Presentation

New Survey Methods: Tools to Dig for Gold

Surveys are widely used by scholars, companies, and public policymakers to generate invaluable insights. Despite the popularity of surveys, there are several biases that can affect the validity of self-reported data. In his inaugural address,

Martijn de Jong discusses how new survey methods can help to extract valid information from surveys. Several examples are presented that showcase the relevance of better research design and careful statistical modeling of the response process. In addition, De Jong addresses some commonly held perceptions about the ability to make causal inferences with survey data.

From the report:
Let’s go back in history a bit to see why survey researchers make allusions to causality. In an Econometrica paper from the 1970s, Goldberger defines a structural equation as one representing a causal relationship, as opposed to a relationship that simply captures statistical associations (Goldberger 1972). The article’s conclusion contains a fascinating sentence: 

“economic, sociological, psychological, and political theory all have something to say about the causal links…” (p. 999).........


Download (pdf): New Survey Methods: Tools to Dig for Gold

Source: RePub


Saturday, June 1, 2013

Crossing the street in traffic

Crossing the street in traffic....
We've all done this: you’re in a hurry, so instead of waiting for the “walk” sign you look both ways and see that the nearest cars are far enough away that you can cross safely before they arrive where you are. You start walking and (I’m guessing) make it across just fine.

  1. Did you know (with absolute certainty) that the cars you saw in the distance weren't moving fast enough to hit you? If so, how did you come to know this? If not, how could you possibly justify making a decision like this, given the extremely high stakes? After all, you were literally betting your life ...
  2. Can logic help us understand how a rational person could make a risky decision like this, despite not having perfect knowledge of all relevant factors?

The street-crossing example is chosen for the vivid consequences of making a wrong decision,
but less dramatic examples would make the point. We almost never know with absolute certainty what the consequences of our actions will be, but we usually manage to make reasonably confident decisions nonetheless — and most of the time we choose right. This needs explaining.

Original Source:
Probabilistic reasoning and statistical inference:
An introduction (for linguists and philosophers)

What is Risk?

Sometimes it makes sense to go back to to your roots and ask yourself, what is RISK really?


Enjoy!

Original Source: What is Risk? (pdf)

Saturday, October 22, 2011

Top 10 default retirement age risks for employers

The abolition of the default retirement age will have several knock-on effects for employers. What is most at risk?

source

Friday, September 2, 2011

Don’t Stop Thinking About Tomorrow

A short quiz:
If you plan to eat hamburgers throughout your life and
are not a cattle producer, should you wish for higher or
lower prices for beef? Likewise, if you are going to buy a
car from time to time but are not an auto manufacturer,
should you prefer higher or lower car prices? These
questions, of course, answer themselves. But now for the
final exam: If you expect to be a net saver during the
next five years, should you hope for a higher or lower
stock market during that period? Many investors get this
one wrong. Even though they are going to be net buyers
of stocks for many years to come, they are elated when
stock prices rise and depressed when they fall. In effect,
they rejoice because prices have risen for the
“hamburgers” they will soon be buying. This reaction
makes no sense. Only those who will be sellers of equities
in the near future should be happy at seeing stocks rise.
Prospective purchasers should much prefer sinking
prices.”

Source

Tuesday, July 5, 2011

Stocks Are Less Risky Than Bonds

It is not stock investing that is risky. It is valuation-uninformed stock investing strategies that are risky. The risks of stocks can be largely avoided by those willing to give consideration to the effect of valuations on long-term returns. It is much harder for investors to avoid the risks of bonds, since inflation is unpredictable and constitutes the biggest risk for bond investors. For the valuation-informed investor, bonds are more risky than stocks.

source

Saturday, June 4, 2011

Hedgefunds selling Alpha as Beta?

In a desperate market everything seems possible.
Even selling Alpha as Beta...

Source1

Friday, May 27, 2011

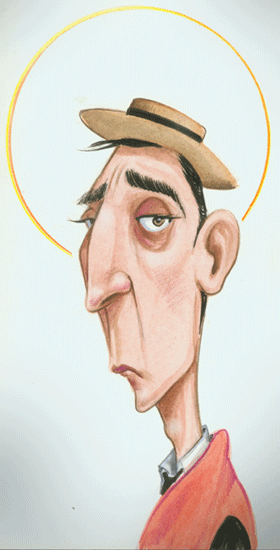
Patron saint of actuaries

St. Buster is the patron saint of actuaries.


source

Sunday, March 27, 2011

What is Risk?

Peter L. Berstein, author of Against the Gods: The Remarkable Story of Risk, explains it pretty well.  He says by definition risk is a measure of the unknown, and because of that it is silly to presume and act as if we know what the future holds.  Risk management really is understanding that the future is uncertain, and preparing ourselves and our institutions to deal with the times when things are different from our expectations.

Source

Saturday, March 26, 2011

A survey of migration

Despite a growing backlash, the boom in migration has been mostly good for both sending and recipient countries, says Adam Roberts (interviewed here)

source

Friday, March 18, 2011

Happiness extends life expectancy

World life expectancy has risen by around 20 years in the last 50 years. This period has also witnessed rising happiness levels around the world suggesting that happiness might be one of the causes behind the decline in mortality. We investigate the relationship between happiness and mortality using the German Socio-Economic Panel. We consider doctor visits, self-reported health, and presence of chronic illness as health measures. After controlling for initial health conditions, we find that happiness extends life expectancy. 10 percent increase in happiness decreases probability of death by four percent, and this effect is more pronounced for men and younger people. Happiness plays a more important role for chronically ill people in decreasing mortality than for those who are not chronically ill. The positive influence of happiness on mortality can offset the negative impact of chronic illness. Marriage decreases mortality and this effect appears to work through increased happiness.

Source

Saturday, March 12, 2011

Frequency of Severe Terrorist Events

In the spirit of Richardson’s original (1948) study of the statistics of deadly conflicts,we study the frequency and severity of terrorist attacks worldwide since 1968.

We show that these events are uniformly characterized by the phenomenon of scale invariance, i.e., the frequency scales as an inverse power of the severity.

We find that this property is a robust feature of terrorism, persisting when we control for economic development of the target country, the type of weapon used, and even for short time-scales. Further, we show that the center of the distribution oscillates slightly with a period of roughly ≈ 13 years, that there exist significant temporal correlations in the frequency of severe events, and that current models of event incidence cannot account for these variations or the scale invariance property of global terrorism.

It has been suggested that the ≈ 13 value may be related to the modal life-expectancy of the average terrorist group. However, we caution against such conclusions for now, as these aforementioned variations on our analysis can shift the peak by several years.


Our analysis suggests that the changes in event frequencies have not been evenly distributed with respect to their severity, but rather that less severe
attacks are now relatively more frequent, while the frequency of “major” or tail events has remained unchanged.

Finally, we describe a simple toy model for the generation of these statistics, and briefly discuss its implications.

Source
Monday, March 7, 2011

Pension Fund: Just Bonds please.....

"My message is simple: Almost every corporate pension fund should be entirely in fixed dollar investments. A pension fund has special tax status, but this tax status has no value if the pension fund is invested in stocks. On the other hand, a pension fund’s special tax status has great value if the pension fund is invested in short-term paper, long-term bonds or insurance contracts."
Fischer Black1


Source: Back to Black

Saturday, October 16, 2010

Survival Simulation

Try it for yourself: How long will you survive...?

Calculate!

Saturday, October 9, 2010

Risk premiums must be taken as earned, and never capitalized

Defined Benefit pension funds is a time bomb waiting to explode. Now a new study suggests that we don't even know how big the problem is.

Unrealistic return expectations of 8%, and an equity risk premium of 8.3%.....
If an actuary is told that the equity risk premium is 8.3% he will build it into his models and assume, come hell or high water, that stocks will earn 8.3% over bonds over the long run.

Whay about the old actuarial rule that “Risk premiums must be taken as earned, and never capitalized.”

Source: How Big Is the Pension Time Bomb?

Unemployment graphics

Sometimes one picture is worth a thousand words....

Will it lead to a double dip......?

Source

update

Monday, May 24, 2010

Bank Failures and Sovereign Debt

An analysis of the more and less important determinants of banking crises causing sovereign debt crises. Some careful conclusions can be drawn from the nationalization and guarantee variables. The focus is on the solvency of countries rather than the more often applied output gap. The debt to GDP behaved as in earlier research. History showed that banking crises can lead to extreme deviations in debt to GDP. Significant changes in debt to GDP do not always lead to sovereign debt crises. Bank failures in the USA are significantly related to debt to GDP over time.

Download: SOVEREIGN GUARANTEES, BANK FAILURES AND RECEIVERSHIP: Solution or increasing risk?

Source: Erasmus Thesis

Saturday, May 22, 2010

Black Swan Statistics

Risk Modeling modern style is all about 'Predicting Instability'.

A "Black Swan", an event that is rare and difficult to predict, which could reflect either a sudden and large shift in the variance or the mean of a random variable.  A large shift in the mean or the variance of a random variable would mean an observation falling in the tails of the distribution.We would assume that a Black Swan is a large and a sudden change in the second moment.  That is a rare and highly improbable large change in the conditional variance of relevant macroeconomic data.      


The test statistics that are available to quality control engineers entail an interrogation of the real time data as they are observed; they sound alarm bells when the moments shift suddenly with high probability.
'Predicting Instability' provides a framework based on a statistic for the Sample Generalized Variance, which is useful for interrogating real time data and to predicting statistically significant sudden and large shifts in the conditional variance of a vector of correlated macroeconomic variables. Central banks can incorporate the framework in the policy making process.

Download: Predicting Instability
source: MPRA